

Preparing for FinCEN Reporting (RRE)
- Discount Partner Programs -

Free Resources
Free FinCEN Tools for Title and Settlement
Recorded FinCEN Training Webinar
Learn everything you need in 45 minutes about FinCEN’s new real estate reports with a free pre-recorded webinar.
Transaction Exemption Checker

Check whether your transaction requires a FinCEN report in about 30 seconds using a free tool with four quick questions.
Customer Explainer Templates

Templates for buyers and sellers to explain FinCEN reporting requirements with easy best-practice language.
Report Billing Rules by State
Check if you can pass-through costs to settlement statements in your state to avoid absorbing FinCEN compliance costs.
Real Estate Agent Guide to FinCEN

Share this with real estate agents to help them speak with clients to prepare buyers and sellers for the FinCEN filing.
Designation Agreement Template
Download a free designation agreement to transfer filing responsibility to others in the reporting cascade.
Get Ready for FinCEN in 45 Minutes
FinCEN Masterclass Webinar Video
Prepare your team in 45 minutes to confidently handle the FinCEN Real Estate Report through a focused webinar masterclass covering required workflows, best practices, and free implementation resources.

Everything You Need to Know
Introduction to FinCEN's Real Estate Reporting
What Is FinCEN’s Real Estate Report?
FinCEN’s Real Estate Report is a new federal reporting form for certain residential real estate transfers. It applies when a home or other covered residential property is transferred without traditional bank financing, and the buyer is a legal entity or a trust, not a natural person.
The goal is to provide visibility into anonymous real estate purchases that can hide money laundering or other illegal activity or compromise national security.
For settlement agents, some transactions will require you, or another professional involved in the closing, to collect specific information and submit a report to FinCEN.
Why FinCEN Is Requiring It
FinCEN has long viewed residential real estate as a risk area when buyers can use entities or trusts to hide who really owns or controls the purchase. The Real Estate Report is meant to add transparency, especially in deals that do not have a regulated lender doing its own anti money laundering checks.
When the Requirement Starts
FinCEN delayed the start date. Reporting under the Residential Real Estate Rule begins March 1, 2026. Transfers that close before that date are exempt from the filing requirement.
What Changed From the Current GTO Reports
Right now, some reporting exists through Geographic Targeting Orders that apply only in certain locations and scenarios. FinCEN is moving toward a single nationwide rule with one standard report and a more consistent process for covered transactions.
Does Your Closing Require a Real Estate Report?
- RER Exemption Checker -
Is the Property Residential?
Applies to all 50 states, DC, Puerto Rico, U.S. territories, and tribal lands.

Does the property fall into any of these categories?
Who Is Buying the Property?

Select the type of buyer (or transferee for no-cost deeds) receiving the real estate:
How Is the Buyer Paying?

When buyers or transferees have lenders with AML programs involved in the transaction, no report is required because that lender's AML program already reports ownership details to the government. Select an option below to see if a lender exemption qualifies.
Exemptions
Do ANY of these other exemptions apply to your transaction:
- Transfer is due to a death (will, trust, inheritance) ⓘA transfer resulting from the death of an individual, whether pursuant to the terms of a will, the terms of a trust, the operation of law (such as transfers resulting from intestate succession, surviving joint owners, and transfer-on-death deeds), or by contractual provision (such as transfers resulting from beneficiary designations). These transfers are exempt from reporting.
- Divorce/dissolution settlement ⓘA transfer incident to divorce or dissolution of a marriage or civil union (such as transfers required by a divorce settlement agreement) is exempt from reporting.
- No-cost transfer to seller's or spouse's own trust ⓘA transfer for no consideration made by an individual, either alone or with their spouse, to a trust of which that individual, that individual's spouse, or both, are the settlors or grantors. These transfers are exempt from reporting.
- Transfer to bankruptcy estate ⓘTransfer of property to a bankruptcy estate as part of bankruptcy proceedings. These transfers are exempt from reporting.
- Court-ordered or supervised transfer ⓘAny transfer ordered by or supervised by a U.S. court, including probate, guardianship, or other judicial proceeding is exempt from reporting.
- Easement (no property transfer) ⓘA transfer that is a grant, transfer, or revocation of an easement is exempt. Exemption does not include transfer of the underlying property.
- 1031 exchange to Qualified Intermediary ⓘA transfer to a qualified intermediary for the purposes of a like-kind exchange for purposes of Section 1031 of the Internal Revenue Code is exempt.
- Buyer is exempt regulated entity or its subsidiary (hover for list) ⓘ Includes any of these:
1) Securities reporting issuer (public company);
2) Bank;
3) Credit union;
4) Depository institution holding company;
5) Money services business;
6) Broker or dealer in securities;
7) Securities exchange or clearing agency;
8) Other Exchange Act registered entity;
9) Insurance company;
10) State-licensed insurance producer;
11) Commodity Exchange Act registered entity;
12) Public utility;
13) Financial market utility;
14) Registered investment company;
15) Subsidiary of any of the above. - Buyer is government authority ⓘBuyer is any federal, state, local, tribal, or foreign government entity or agency.
- Trust is a securities reporting issuer or has a public company trustee ⓘExempt if the trust itself is a securities reporting issuer, or if any trustee is a securities reporting issuer. A subsidiary of such a trust is also exempt.
- No reporting person involved in transfer (hover for list)ⓘExempt from reporting if none of the following parties are involved in assisting the transfer:
1) Closing or settlement agent named on the closing or settlement statement;
2) Preparer of the closing or settlement statement;
3) Person who files with the recordation office the deed or other transfer instrument;
4) Underwriter of the owner's title insurance policy;
5) Person who disburses the greatest amount of funds for the transfer;
6) Person who evaluates the status of title;
7) Preparer of the deed or, if no deed, the instrument that transfers ownership (for co-op shares, the stock certificate preparer).
Filing Needed
You need to file a report with FinCEN.
Want to offload filings to our experts?
- ✓ Only billed later for closed transactions
- ✓ 100% FinCEN filing guarantee
- ✓ Expert support with 150,000 filings complete
- ✓ Many customers pass through costs to closing
- ✓ Order reports in a minute plus full tracking
Filing Not Needed
You do not need to file a report with FinCEN.
Want to offload filings to our experts?
- ✓ Only billed later for closed transactions
- ✓ 100% FinCEN filing guarantee
- ✓ Expert support with 150,000 filings complete
- ✓ Many customers pass through costs to closing
- ✓ Order reports in a minute plus full tracking
Most transactions will not require a report but approximately 15% will fall into this new requirement. Penalties currently range from $1,300 to $278,000 for failing to file, making identifying transactions needing reports essential.
This tool will check transactions in 30 seconds for free.
Reports are required for any transaction involving U.S. residential property, a buyer that is not an individual, and no traditional bank-type mortgage.
A Real Estate Report is required when all of these are true. You can check these when you open a file:
- The property is residential real property (including land) in the United States
- The deal includes a transfer of an ownership interest
- At least one buyer is a legal entity or a trust
- The transfer is non-financed (no AML obligated lender with an NMLS number)
- No exclusion or exemption applies
If you hit all five, treat it as reportable and start information collection early.
Step 1: Confirm the property is covered by the definition of residential
Covered residential real property includes common file types like these.
- Single-family homes and townhouses
- Condos and co-ops, including units in large buildings
- Buildings designed for one to four families
- Land where the buyer intends to build a one to four family residence
- Mixed-use property can still qualify if it includes a one to four family residence
If the property is outside the United States, this rule does not apply.
Step 2: Confirm it is a transfer of an ownership interest
A transfer is any change in ownership shown by a deed. For co-ops, it can be shown by shares, membership, a certificate, or a similar ownership document. There is no dollar threshold. A low-price sale can still be reportable. A gift can still be reportable.
Step 3: Identify who is taking title
This rule focuses on the buyer type.
- A transfer to an individual is not covered and does not require a report
- A transfer is potentially covered when at least one buyer is a legal entity or a trust. Examples include an LLC, corporation, partnership, association, estate, or a trust. Domestic and foreign entities and trusts can be covered.
- If title is taken in the name of a trustee acting as trustee, it can still count as a transfer to a trust.
- If there are multiple buyers, the deal can be reportable even if some buyers are exempt. As long as at least one buyer is a reportable entity or reportable trust, the transfer is treated as reportable.
Step 4: Check the financing
A transfer is treated as non-financed when it does not involve credit that meets both of these conditions.
- The loan is secured by the property
- The loan is made by a financial institution that must have an AML program and file SARs
All-cash is the simplest example of non-financed.
Be careful with private lending. If the only financing comes from a lender that does not have AML program and SAR obligations, the transfer is treated as non-financed and may be reportable. Also watch for deals where not all transferees are covered by the loan. The rule looks at whether credit is extended to all transferees.
If you are unsure whether the lender is the type that carries AML and SAR obligations, do not guess. Ask the lender or check with this free tool.
Step 5: Check for exclusions and exemptions
Some common transfers are excluded. Here are examples you will see.
- Easements
- Transfers due to death, including will or trust distributions, operation of law, or transfer-on-death deeds
- Transfers tied to divorce or dissolution
- Transfers to a bankruptcy estate
- Transfers supervised by a U.S. court
- A no-consideration transfer by an individual, alone or with a spouse, into a trust where the same individual or spouse is the settlor or grantor
- Transfers to a qualified intermediary for a 1031 like-kind exchange
- Transfers where there is no reporting person involved in the closing roles covered by the rule
There are also exemptions based on the buyer being a highly regulated entity or trust. Do not assume an entity is exempt just because it is familiar or well known.
Build an intake step that identifies the buyer type and flags exemption status early. You can use this free tool to make it easy.
How to Avoid Missing a FinCEN Real Estate Report Filing for Title and Settlement Agents
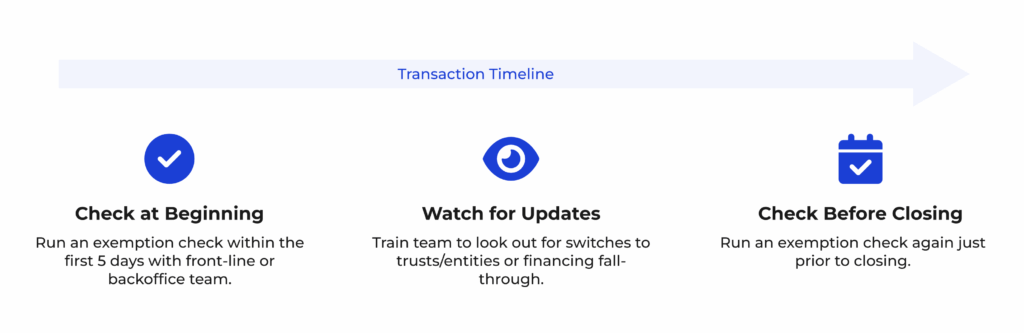
Most missed filings happen for one reason. The file was not reportable when it opened, then something changed and nobody re-checked it.
That is why a one-time screen at file open is not enough. You need a simple control that catches reportable files at the start, catches changes during the file, and catches anything that slipped through before closing. This is what we call the compliance sandwich.
Why files flip from not reportable to reportable
In real operations, changes cause most surprises. Example (more below): The buyer decides to take title in an LLC or trust late in the process
If you only check at intake, you can miss these. If you only check at the end, you lose time and you end up collecting sensitive information when everyone is least willing to deal with it.
The Compliance Sandwich in three steps
Step 1: Check at file open and mark the transaction
Run a quick screen as soon as you have enough details. You are not trying to become a regulatory expert. You are trying to answer one question early. “Does this file require a Real Estate Report if it closed today.” Tip: The exemption checker can tell you this in a minute for free.
A practical screen looks like this.
- Is it U.S. residential real property?
- Is any buyer a legal entity or a trust?
- Is it non-financed under the rule?
- Do any exemptions apply?
Then mark the file based on what you find.
- Report required
- Report not required
This marking step matters. It turns a compliance question into an operational status your team can see. This tool can help you with this step.
Step 2. Watch for changes during the file and re-check immediately
Most misses happen in the middle. The best way to prevent this is training plus a short list of triggers that forces a re-check.
Your team should re-run the screen the same day if any of these happen.
- Vesting changes to an LLC or trust
- A new transferee is added
- Financing terms change, lender drops, or the deal becomes cash
- The buyer switches from traditional financing to private or hard money style financing
- The buyer’s counsel sends updated instructions that change how title will be held
Keep the rule simple for staff. If it changes who is buying, or how the deal is financed, re-check. This avoids arguments later about whether someone “should have known.” The system makes it automatic.
This pre-recorded training webinar can teach your team how to watch out for these in 45 minutes.
Step 3. Re-check right before closing as a final catch
This is the second piece of bread. It catches the late surprises and the human misses.
Do the final check during your closing prep. The goal is not to redo the entire file. The goal is to confirm the three items that most often changed.
- Final vesting and buyer type
- Final financing status
- Any exemptions that were assumed earlier
If the file is reportable, you want to know before closing, not after. Post-closing collection is where response rates drop and frustration spikes.
How to implement the Compliance Sandwich without adding chaos
You can run this with a light process. It does not need a new department. Use these basics.
- Add a visible field in your production system for Real Estate Report status
- Require the Step 1 screen at file open for every residential file
- Require a re-check any time a trigger occurs
Require the Step 3 re-check in the final closing checklist - Assign a backup owner for when the primary closer is out
A realistic outcome if you do this well
You catch reportable files early. You reduce last-minute customer friction. You avoid “surprise compliance work” that steals time from closing. Most important, you avoid missed reports that create liability later.
Who Has to File the Real Estate Report?
Only one business files the Real Estate Report for a reportable transfer. FinCEN calls that business the reporting person. Even if several parties touch the file, you do not want duplicate reports. You want one clear owner.
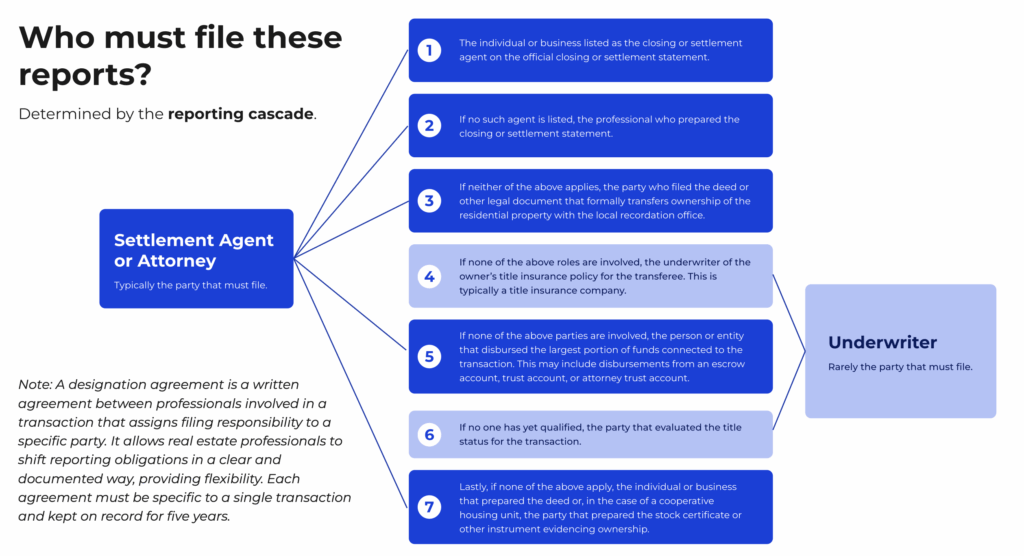
There are two ways to determine who files, either use the reporting cascade or use a written designation agreement to assign filing responsibility to someone else in the cascade. A designation agreement template is available here.
How the reporting cascade works
The reporting cascade is a fixed order. You start at the top and stop as soon as you find a person involved in the transfer who performs that function. That person is the reporting person unless the parties use a designation agreement. That person can use a third-party for filings. If they do that, they should make sure that third-party will guarantee the filings to offset their liability (FincenRealEstateReport.com offers this guarantee).
Here is the cascade in order.
1. The person listed as the closing or settlement agent on the closing or settlement statement.
2. If nobody above applies, the person who prepares the closing or settlement statement.
3. If nobody above applies, the person who files the deed or other ownership transfer instrument with the recordation office.
4. If nobody above applies, the person who underwrites the owner’s title insurance policy for the buyer.
5. If nobody above applies, the person who disburses the greatest amount of funds tied to the transfer, including from escrow or a trust account.
6. If nobody above applies, the person who provides an evaluation of the status of title.
7. If nobody above applies, the person who prepares the deed or other legal instrument that transfers ownership. This includes the person who prepares the stock certificate for a co-op transfer.
If none of these functions are performed for the transfer, then no report is required.
What this usually means for settlement agents
In many transactions, the answer is straightforward. If your company is listed as the closing or settlement agent on the settlement statement, you are at the top of the cascade. That usually makes you the reporting person by default.
If there is no settlement statement, or no settlement agent listed, the cascade keeps going until it finds the first qualifying role.
Using a designation agreement
Sometimes the parties in the cascade want a different reporting person. FinCEN allows that, but only through a written designation agreement. This option is meant to reduce burden and make sure the party best set up to file takes the lead.
A designation agreement does not pull in a random third party. The designated reporting person still has to be a person who performs one of the cascade functions in that same transfer. That person may still use a third-party to manage the filing for them.
What a designation agreement must include
There is no required format, but the agreement must be in writing and it must identify all of the following. An example is available here.
- The date of the agreement
- The name and address of the seller
- The name and address of the buyer entity or buyer trust
- The property being transferred
- The name and address of the designated reporting person
- The name and address of every party signing the agreement
A separate designation agreement is required for each reportable transfer. The person who would have been the reporting person under the cascade must be a party to the agreement. Other cascade parties do not have to sign it.
The designation agreement does not get filed with the Real Estate Report. It must be kept in the file for record retention.
Note: You do not need designation agreements for third-party filing service providers. FinCEN specifically addresses this here and this is benefit to settlement. Third-parties can accept liability in their commercial terms instead, which also means you can skip the 4-page agreement for each transaction. FinCEN has approved third-party filing but simply does not want them listed in designation agreements.
Two common examples
Example 1: Your office is listed as the settlement agent on the settlement statement. The deal is reportable. No designation agreement is used. Your office is the reporting person and you file the report.
Example 2: There is no settlement agent listed, but the deed is recorded by a party involved in the closing. Under the cascade, that deed filer would be the reporting person. The deed filer and the title insurance underwriter decide the underwriter should file for that specific transfer. They sign a designation agreement and the underwriter becomes the reporting person.
Practical steps to avoid confusion on day one
- Decide your default position. If you are listed as settlement agent, assume you file unless a designation agreement is signed
- If you want another party to file, get the designation agreement signed early, not at the end of the closing
- Put one person in charge of confirming who the reporting person is before you start collecting the full data package
How to Prepare for FinCEN’s Real Estate Report in 3 Steps for Title and Settlement Agents
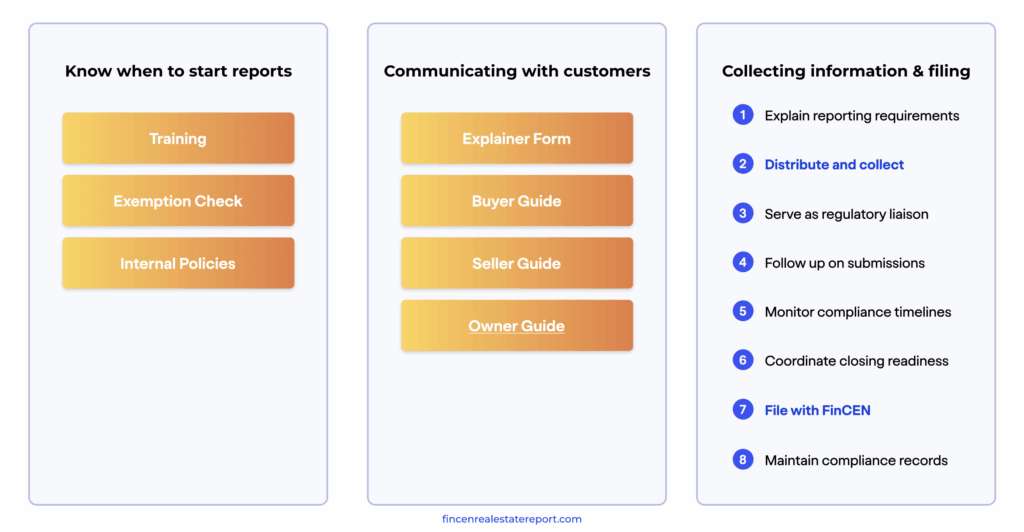
A clean rollout comes down to three moves. First, you flag the right files early and keep that flag accurate. Second, you tell customers what is coming before you request sensitive details. Third, you run filing as a controlled workflow with a clear owner, a clear “ready” standard, and a simple post-close trigger.
Step 1. Mark transactions early and keep the mark current
Start by turning “Is this reportable?” into a visible status on every residential file. Your staff should never have to rely on memory or guess whether someone already checked it. A simple status works well. Reportable, not reportable, or re-check required.
At file open, run the quick qualifier as soon as you have basic details. Confirm the property is U.S. residential real estate. Confirm whether any buyer is a legal entity or a trust. Confirm whether the transfer is non-financed under the rule. Then scan for exemptions. If it is reportable, mark it and start information collection right away. If it is not reportable, document why. If you do not have enough information yet, mark it as re-check required so the file does not drift.
The part that keeps you safe is updating the mark when the file changes. Train staff to re-check any time vesting or financing changes. Two scenarios cause most late surprises. The buyer adds an LLC or trust near the end for estate planning or liability reasons. Financing falls through and the buyer proceeds without a qualifying lender. Either change can flip the file into reportable. When that happens, re-run the qualifier the same day and update the status.
Finally, make one last re-check part of your closing prep. Confirm final vesting and final financing status. A short pre-close check catches the files that slipped through and avoids post-close chasing.
Step 2. Communicate with customers before you ask for sensitive information
Customer friction usually starts when the first request feels sudden. You avoid that by sending a short explainer as soon as the file is marked reportable. The explainer should set expectations, explain why you are asking, and explain how to keep the closing on track.
Keep the message simple and calm. Say that certain transactions require a federal report. Say that it is routine and not a sign they are being targeted. Tell them what they will be asked to provide, such as identity details and ownership information for entities or trusts. Tell them why timing matters, because collecting after cash or keys is harder and can create delays.
Send this early enough that people can respond without panic. When a buyer is using an entity or trust, there may be multiple people who need to provide details. That takes longer than a single individual buyer. If the buyer has counsel, include the buyer’s attorney as early as possible, since counsel often drives vesting choices.
You also want your internal team to sound consistent. Use one standard explainer template, and keep a short internal answer guide for the most common questions. This prevents your closers from improvising explanations and reduces the time spent on repeated calls.
Step 3. Run the filing process as a controlled workflow
Once a file is marked reportable, treat the process like a small project with a clear owner. The first operational decision is who files. Confirm the reporting person early so you do not collect information under the wrong assumption. If a designation agreement will be used, get it signed early and store it in the file.
Next, define “FinCEN clear to close” for your shop. This should be a real readiness gate. A reportable file should not be treated as ready until the required information is complete, including the beneficial ownership information and the required written certification from the transferee or the transferee’s representative. If you allow reportable files to close without this, you are choosing post-close follow-up work, and response rates drop.
After closing, use one post-close trigger so filing does not get lost on a busy day. The file owner should have a simple way to confirm the closing occurred and initiate submission promptly. Do not operate as if the deadline is the goal. File soon after closing when the details are fresh and your team is still in rhythm.
Finally, lock down record retention. Store the signed beneficial ownership certification and any designation agreement in a consistent, secure location tied to the file. Keep access limited to staff who need it. Make retention a normal part of file closeout so it happens every time.
A fast implementation checklist that works
You can test and implement this without a major system change.
- Add one Real Estate Report status field to your production system.
- Write your initial quick qualifier and your re-check triggers into your procedures.
- Add the pre-close re-check to your closing checklist.
- Finalize one customer explainer template and a short internal answer sheet.
- Assign an owner and a backup for reportable files.
- Then run one practice file end to end so the team sees what “marked, communicated, clear to close, closed, filed” looks like in real life.

FinCEN Clear to Close Checklist for Title and Settlement Agents
A Real Estate Report does not get filed until after closing, but the work that makes filing possible has to be done before closing. “FinCEN clear to close” is the internal gate that confirms you have what you need, the reporting person is confirmed, and the file can close without creating a compliance mess afterward.
What “FinCEN clear to close” should mean
A reportable file is FinCEN clear to close when the required reporting information has been collected and is complete enough to support a timely, accurate submission right after closing. It is not a vague feeling and it is not the same as “we think we can probably get it later.” It is a deliberate status that signals the file is ready from a reporting standpoint.
The reason this matters is behavioral. Once buyers and sellers feel the deal is effectively done, they become much less willing to answer questions about identity, ownership, and funds movement. Collecting before closing protects your timelines and keeps customer frustration lower.
The minimum items required to mark a file clear
Start by confirming the deal is still reportable. This should be a short confirmation using the final vesting and final financing status. If the buyer switched into an entity or trust late, or the financing fell through, the file can flip into reportable status. You want to catch that before documents go out.
Next, confirm who the reporting person is. Your file should show that you have identified the reporting person under the reporting cascade, and that any designation agreement has been signed and stored if you used one. This avoids duplicate work, confusion about responsibilities, and last-minute handoffs.
Then confirm the core information package is complete. You should have complete and consistent property and transfer details, seller information, buyer entity or trust information, and signing individual information. You should also have the payment and source of funds information required for the report at the level you plan to submit.
The file should also include beneficial ownership information, and this is where teams most often get stuck. Your clear to close gate should require the beneficial ownership information and the written certification from the transferee or the transferee’s representative. If that certification is missing, you do not have a clean basis to rely on the beneficial owner information, and you have a higher risk of delays and rework later.
Finally, complete a quick quality control review. This does not need to be complex. It should be consistent. Your reviewer is checking that names match across documents, buyer type is correct, and the information set is not obviously missing required items. QC is also where you catch mismatches created by late changes, such as a vesting update that never made it into the reporting data.
A simple status system that keeps files organized
Clear to close works best when it is visible. If you can only tell status by opening emails, you will lose track.
Use a small set of statuses that staff can apply consistently, such as these:
- Not reportable
- Reportable and collection started
- Waiting on customer submission
- Waiting on internal review
- FinCEN clear to close
- Closed and ready to file
- Filed
- Retention complete
This makes it easy for managers to scan active files and identify where bottlenecks are forming.
Timing rules that prevent last-minute problems
A workable internal rule is that a reportable file should reach FinCEN clear to close before you treat it as ready for final scheduling. That means the customer communication goes out early, collection starts early, and you do not wait until the week of closing to request beneficial owner details.
If information is incomplete close to closing, you need a consistent escalation. First, send a clear reminder that states what is missing and when you need it. If the file is within a short window of closing and the missing item is still not received, treat it as a closing readiness issue, not a casual follow-up.
Common failure points to train your team on
Most files fail clear to close for predictable reasons. The buyer changes vesting late. Financing falls through. The buyer provides entity details but does not provide the individuals behind the entity or trust. One owner in a multi-owner structure goes quiet. The source of funds changes after initial submission and nobody updates it.
If staff expect these issues and know how to react, they stop being emergencies
What you get when this is enforced
When FinCEN clear to close is used consistently, reportable files run like a controlled process. You reduce post-close chasing, reduce customer complaints tied to late requests, and you avoid the operational risk of missed or late filings. The closing team stays focused on closing, and the reporting workflow stays predictable.
What Information You Need to Collect for a Real Estate Report
Once a file is flagged as reportable, your next job is simple to describe and easy to underestimate. You need enough detail to identify the property, the seller, the buyer entity or trust, the people behind that buyer, and how the money moved.
If you wait until the week of closing to gather this, you will create unnecessary friction. Build it into intake so you are collecting it while everyone is still responsive. We recommend sending this introduction form to make the process easy and understandable for buyers and sellers.
Step 1: Lock down the property and closing basics
Start with the items you already control.
- Date of closing
- Property street address, city, state or territory, and ZIP code
- Legal description type
- Legal description copied from the deed or other transfer document
Best practice that saves time later is to copy the legal description directly from the deed as soon as the draft is available. Do not rewrite it.
Step 2. Collect transferee information for the buyer entity or trust
This is the buyer on title, not the person signing emails. You will typically need the following.
- Transferee type
- Legal name and any alternate name
- Principal place of business address if it is an entity
- Country or jurisdiction and state or territory
- Identification type and identification number
If the transferee is a trust, you also need trust details.
- Date the trust instrument was executed
- Whether the trust is revocable
You also need the total consideration paid for the transfer. In plain terms, this is the total amount paid or to be paid for the property as a whole. If it is a gift or other no-consideration transfer, you will record that instead.
Step 3. Identify the people tied to the transferee
This is where most delays happen, because people assume the entity name is enough. It is not.
Beneficial owners for an entity
For a transferee entity, a beneficial owner is any individual who meets either of these tests on the closing date.
- They exercise substantial control over the entity
- They own or control at least 25 percent of the ownership interests
For each beneficial owner, you should expect to collect.
- Full legal name
- Date of birth
- Residential address
- Country or jurisdiction of citizenship
- Taxpayer identification number
- Identification type and identification number when required by your process
A practical rule is to ask the buyer for a short ownership and control summary that names the individuals who meet the tests. Do not try to reverse engineer it from a stack of formation documents at the last minute.
Signing individuals: The report captures certain individuals who sign documents on behalf of the transferee in the transaction. For each signing individual, be ready to collect additional information.
- Authorization capacity (from FinCEN’s list)
- Name of employer, principal, or partnership when applicable
Beneficial owners for a trust
For a transferee trust, beneficial owners are based on roles. At the time of transfer, include any individual who fits one or more of these categories.
- A trustee
- Any individual with authority to dispose of trust assets
- A beneficiary who can demand or withdraw substantially all trust assets, or who is the sole permissible recipient of income and principal
- A grantor or settlor who can revoke the trust or withdraw trust assets
Also include individuals who are beneficial owners of an entity or trust that holds one of those roles. This is the look-through situation. It is common when a corporate trustee is involved.
For each trust beneficial owner, collect the same core items you collect for entity beneficial owners. Name, date of birth, residential address, citizenship, and taxpayer identification number are the basics.
Step 4. Collect transferor information for the seller
Most of the time, the seller is an individual and this is straightforward. Still, gather it early.
- Full legal name
- Date of birth if an individual
- Residential address if an individual
- Principal place of business address if an entity
- Country or jurisdiction and state or territory
- Identification type and identification number
If the transferor is a trust, you will also record the trust instrument executed date and identify the trustee or trustees.
Step 5. Capture payment details that explain how the deal was funded
FinCEN cares about the money trail, not just the purchase price. You will record the total consideration paid and then capture details about payments made by or on behalf of the transferee. For each payment, be ready to document.
- Payment amount
- Payment method
- Account number when applicable
- Financial institution legal name when applicable
- Whether the payment did not come from a financial institution account
- Which transferee the payment is associated with if there are multiple transferees
- Payor information when the payor is not already listed as a transferee
Also flag private or hard money style loans when they are part of the reportable transfer. Do not assume a private loan makes the deal financed under the rule. It often does not.
The buyer and seller pages show how the full-service solution collects this information easily from customers and captures their sign-off for reasonable reliance protection.
How to File the FinCEN Real Estate Report
You file the Real Estate Report after closing through FinCEN’s BSA E-Filing system. The decision you need to make is how you want to run the workflow that leads up to that submission. Most settlement teams land in one of three paths. Manual filing, automated in-house filing, or a full-service option where the collection and submission work is handled for you.
With a manual approach, your team gathers the required information, then completes the Real Estate Report inside the BSA E-Filing process using FinCEN’s form. This works, but it is easy to underestimate the effort. The report includes a large set of fields, and many are conditional based on whether the buyer is an entity or a trust, how payments were made, and who counts as a beneficial owner. The most common issues are missing details, mismatched names across documents, and buyer information that arrives incomplete. Manual filing also depends on your staff catching errors before submission, because fixes later often turn into amendments and more back and forth.
Some larger operations try to automate parts of the workflow in-house. They use structured intake forms, templates, and internal checklists so staff are not reinventing the process on each file. This can reduce rework, but it still requires someone to manage the customer experience. People will have questions, some will submit partial information, and many will ignore the first request until reminders go out. You also need a reliable way to track when a file is ready to close, and when it is ready to file, so deadlines do not get missed.
A full-service workflow removes most of that operational drag by shifting the heavy lifting outside your closing team. In practice, you start the process with a small set of details, often pulled from the purchase agreement or your title system, such as the property address, buyer and seller names, and contact emails. The service then sends secure links to the buyer and seller and walks them through a guided online flow. The form changes based on what they select, so a trust sees trust questions and an entity sees entity questions. Good systems save progress as the customer goes, so they can stop and come back without losing work. They also include clear prompts that explain who to include as beneficial owners, which is where many people get stuck.
Accuracy is where the best automated workflows shine. High-volume filers that submit using FinCEN’s structured filing format can validate data against FinCEN’s technical field rules before submission. That supports live forms that check entries in real time, so obvious issues get caught early. Examples include missing required fields, invalid formats, and conflicts between answers that do not fit together. That kind of validation is harder to replicate with a manual process, because it depends on the reviewer noticing problems after the fact.
A full-service process also reduces the support burden. When customers have questions, they can be routed to a dedicated support channel instead of your closers. Reminders can be automated and tied to the closing date, including a final prompt shortly before closing in case funding accounts or ownership details changed. At the end of the flow, the customer completes the required sign-off and certification, and the system captures an audit trail like time stamps and submission records. After closing is confirmed, the service submits the report promptly and maintains the required records.
For your team, the filing step becomes predictable. Mark the file as reportable, start the process early, watch for a clear-to-close status, then confirm the file closed so submission happens. That is the cleanest way to keep compliance from turning into a last-minute closing problem.
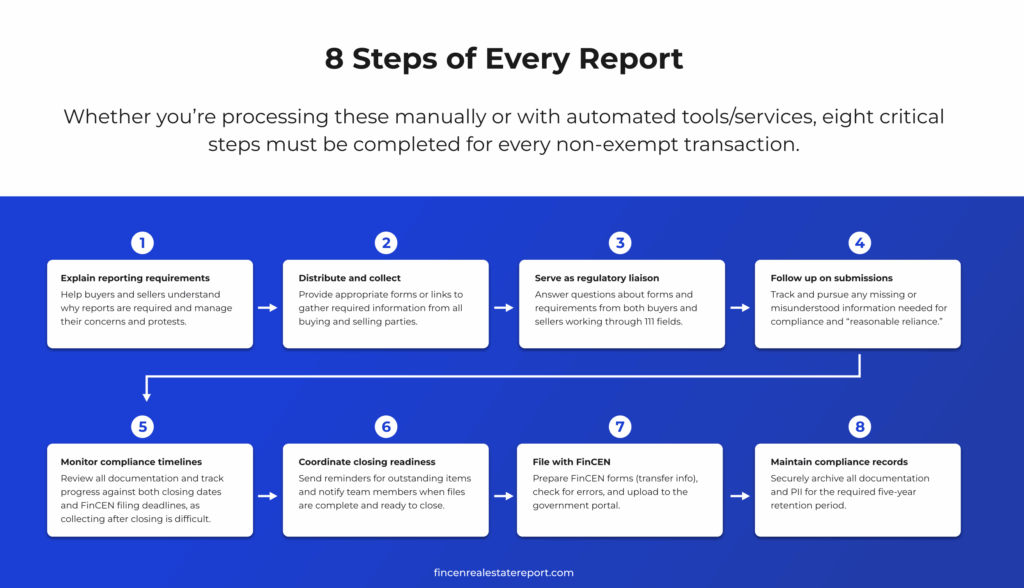
How Settlement Agents Can Reduce $450 and 4 Hours to About 2 Minutes and Under $100
The reason people quote numbers like $450 and three to four hours is simple. A manual Real Estate Report workflow creates work in places that do not look like “filing.” FinCEN’s own analysis of the final rule estimates a multi-hour burden per reportable transfer. Their breakdown includes time to collect and review information and documents, time to complete the report, and time spent confirming who the reporting person is. When you translate that into a real closing pipeline, the work expands fast because you are coordinating multiple people, handling corrections, and tracking deadlines across many open files at once.
Manual workflows usually fail in the same way. The buyer receives a PDF or a loose email request, submits partial information, and then your staff has to become a compliance help desk. People ask who counts as an owner, what to do with trusts, which IDs are acceptable, and why you need account details. Each question is small, but the volume is what creates the time sink. Add one missing beneficial owner and you can spend more time chasing a single file than you spent closing it.
A full-service solution changes the economics by moving those steps out of your office and into a guided, supported workflow. The key difference is that your team stops doing the eight operational tasks and shifts to a short start-and-monitor model. That is where the “two minutes” comes from. It is two minutes of staff time, not two minutes for the buyer to provide their details and not two minutes for the report to exist. Your staff time becomes the scarce resource you protect.
Here is how the full-service approach works in practice
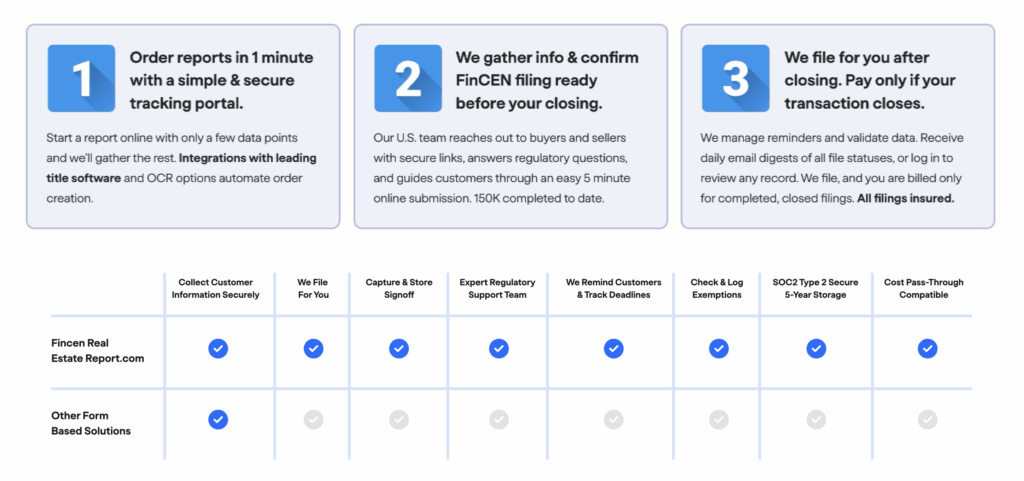
Your team starts a reportable file in about a minute by entering only the basics, or by importing them from your title production software. That usually means property address, buyer and seller names, closing date, and emails. From there, the system sends secure invitations to the buyer and seller. The customer does not see 111 fields. They see a guided flow that changes based on whether they are dealing with an entity or a trust, and it saves progress so they can stop and come back without losing work.
The best full-service flows reduce errors by validating information while the customer is entering it. This is one of the largest advantages of a platform that files at scale. High-volume filers build their forms around the same structured rules used for submission, which makes it possible to catch missing fields, invalid formats, and inconsistent answers before the report ever reaches the submission step. That cuts rework dramatically and reduces the number of “we need you to re-do this form” follow-ups that frustrate buyers and sellers.
Support is the second major lever. When customers get stuck, they can ask questions inside the workflow instead of calling your closer. That keeps your staff focused on closing. It also keeps answers consistent, which matters when buyers are nervous about providing sensitive information. Strong systems also handle reminders automatically and time them to the closing calendar. A practical example is a reminder shortly before closing to confirm or update source of funds information, since that detail is one of the most common late changes.
At the end of the customer flow, the system captures the required sign-off and certification, along with a clean audit trail. After closing, you mark the file as closed and the report is submitted promptly. The platform maintains the required records for retention in a secure way, and the reporting process becomes predictable.
Cost moves the same way as time. A manual workflow is expensive because you pay in staff hours and disruption. A full-service workflow is priced per completed filing, which makes it easier to map costs to a file and pass them through where allowed. Many teams can get the effective per-report cost under $100 with the right pricing structure and volume, and they avoid the hidden cost of pulling closers into repetitive compliance tasks.
The takeaway is straightforward. You are not eliminating work. You are relocating it into a workflow that is designed for data accuracy, customer completion, and deadline control. That is how an office that expects $450 and half a day per report can move to a model where the internal burden is closer to two minutes per file.

Book a Demo
Schedule a demo to explore full-service guaranteed FinCEN filing.
Industry Leader in FinCEN Compliance
Proven & Secure FinCEN Filing Industry Leader
1,000+
U.S. Firms
Use our FinCEN filing products and services today at law firms, accounting firms, fund management services, and real estate services providers.
150,000
Annual Filings
Flow securely through our solutions each year to FinCEN, supporting ongoing compliance for entities and their professional services providers.

SOC2 Type2 Secure
Certification protects client data. This rigorous standard and recurring audits assures security best practices and regular testing for our solutions and services.
40+
State Associations
Including state bar associations, CPA societies, and real estate groups work with our experts for continuing regulatory education courses and services.

